At a glance
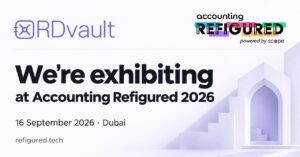
RDvault is exhibiting at Accounting Refigured 2026. The event runs on Wednesday 16 September 2026 at Area57 Events, Al Khayat Avenue, Al Quoz Industrial Area 1, Dubai. The full agenda and tickets are at refigured.tech.
The UAE R&D Tax Credit is already in force. It applies to tax periods beginning on or after 1 January 2026, under Cabinet Decision No. 215 of 2025 (CD 215) and Ministerial Decision No. 24 of 2026 (MD 24).
The credit is non-refundable in Phase 1, and MD 24, Article 2(2) says so expressly. It offsets Corporate Tax and Top-up Tax liability for in-scope group members. Any unused balance can be carried forward under CD 215, Article 6(3), subject to the restrictions in MD 24, Article 5.
Pre-approval from the Emirates R&D Council is mandatory for every R&D project (CD 215, Article 3(1)(b); MD 24, Article 4(1)). The Council’s application portal has not launched yet.
The credit is capped at AED 2,000,000 per tax period. Qualifying expenditure is capped at AED 5,000,000 (MD 24, Article 2(1)). Those two numbers get mixed up all the time, and the difference matters to every calculation built on top of them.
Where to find us
We’ll be on the exhibition floor for the full day, from registration at 09:00 through to closing remarks at 16:00. The programme runs on a single stage, so most of the working conversations happen in the exhibition space. Best times to catch us are the morning break at 11:20, lunch from 13:10, and the afternoon break at 14:30.
Come and find us if you want a technical answer to a specific question rather than a brochure. We’ll have the legislation open on the stand.
Why we’re at this event
Accounting Refigured 2026 is supported by ICAEW, with ACCA and ICAP as education partners, and the programme is CPD certified. Hanadi Khalife of ICAEW is speaking alongside Gavin Aspden of PwC Academy Middle East on building teams that scale without breaking.
That institutional backing matters for a subject like this one. The R&D Tax Credit is a new regime with a mandatory regulatory gate in front of it. The people who’ll decide whether UAE businesses access it correctly are the accountants and finance directors advising them. As an ICAEW Chartered Accountant, this is the room where the regime gets translated into practice.
I wrote up the adviser-side analysis for ICAEW Middle East earlier this year in UAE R&D tax credit regime: key considerations for advisers. What follows is the practical version of that argument, shaped by the questions that actually come up at a stand.
The agenda touches R&D in a few places too. The transfer pricing session with PwC has direct implications for how multinational groups structure their UAE R&D activity, and the treatment of parent-owned intellectual property is one of the more common ways a UAE claim fails before it starts. The e-invoicing and documentation sessions bear on the record-keeping standard the regime expects, which is seven years under MD 24, Article 12.
In the UK, R&D relief is self-assessed. In the UAE, it isn’t.
For advisers who’ve handled UK R&D claims, this is the single difference that changes the most.
In the UK, a company identifies its qualifying activities, calculates the relief, and submits it with its corporation tax return. Scrutiny, if it comes, comes afterwards. The regime is built on self-assessment with retrospective enquiry.
The UAE regime is built the other way round. Pre-approval from the Emirates R&D Council is mandatory for every R&D project (CD 215, Article 3(1)(b); MD 24, Article 4(1)). The Council assesses the project. The Federal Tax Authority assesses the claim through the return cycle. These are two sequential gates operated by two different bodies, not one gate with an audit risk attached.
An adviser who applies UK reflexes to a UAE client will look for qualifying activity first and treat approval as an administrative step. The UAE regime is built the opposite way. Approval is the substantive step. The rest of this post covers what’s in force, what accountants should be asking before they refer a client, and where the legislation still has genuine gaps.
What’s in force from 1 January 2026
The rate table is marginal, not flat
Under MD 24, Article 2(1), the credit is calculated across three bands:
- 15% on the first AED 1,000,000 of qualifying expenditure
- 35% on the next AED 1,000,000
- 50% on the next AED 3,000,000
Applied across all three bands, the calculation produces AED 2,000,000. That’s (15% × AED 1M) + (35% × AED 1M) + (50% × AED 3M). The AED 5,000,000 figure you’ll see quoted in market commentary is the qualifying expenditure ceiling, not the credit ceiling.
Staffing thresholds gate each band
Every band carries a staffing threshold, and both tests have to be met at the same time (MD 24, Article 2(7)):
- Band 1 needs an average of at least 2 R&D staff
- Band 2 needs at least 6
- Band 3 needs at least 14
The average is calculated under MD 24, Article 2(4). A company with AED 5,000,000 of qualifying expenditure and 8 average R&D staff does not reach Band 3, and the 50% rate does not apply to any part of its expenditure.
Minimum expenditure per project
There’s a minimum of AED 500,000 of qualifying expenditure per R&D project (CD 215, Article 5(3)(b)), measured before the 30% staff cost uplift under MD 24, Article 8(3) is applied.
Territorial and activity limits
Only R&D conducted in the UAE qualifies. Where a project runs partly inside and partly outside the State, only the activities carried out within the State can be Qualifying R&D Activities (MD 24, Article 3(3)).
Activity in the social sciences, humanities and arts is excluded (MD 24, Article 3(4)). Grant-funded expenditure is also excluded (CD 215, Article 5(3)(d)).
Non-refundable in Phase 1
MD 24, Article 2(2) states it in terms: the credit is utilised against Corporate Tax and Top-up Tax liability and shall be non-refundable. Top-up Tax utilisation follows CD 215 and Cabinet Decision No. 142 of 2024. Loss-making companies can’t convert the credit to cash in Phase 1. Any unused balance can be carried forward under CD 215, Article 6(3), subject to the restrictions in MD 24, Article 5: either the same person or persons held at least 50% ownership continuously from the period the credit arose to the period it’s used, or, where ownership has changed by more than 50%, the entity carries on the same or a similar business. Listed companies sit outside those restrictions under MD 24, Article 5(2).
The government has signalled a Phase 2 that may introduce refundability, but Phase 2 hasn’t been legislated and there’s no confirmed timeline.
Four questions before you refer a client
Roughly six in ten people at this event advise other businesses. If you’ve got clients doing genuine technical development in the UAE, four questions will tell you quickly whether this subject is live for them.
1. Is the activity technological or scientific in character, and does it resolve genuine uncertainty? MD 24, Article 3(1) sets five conditions and all of them have to be met: novel, creative, uncertain, systematic, and transferable or reproducible. Article 3(2) requires the assessment to be made by reference to the Frascati Manual. Routine software configuration, market research and cosmetic product iteration don’t clear it. This is the gate that disqualifies most enquiries, and it’s worth applying before any figure is discussed. We break down the four eligibility gates in more detail on the site.
2. Can the entity actually use a non-refundable credit? A pre-revenue company with no Corporate Tax liability gains no cash in Phase 1. The credit still has value through carry-forward, but the value is deferred, and a client who’s expecting cash will be disappointed by an accurate answer late rather than early.
3. Does the expenditure clear AED 500,000 on a single project, before uplift? Projects are tested individually under CD 215, Article 5(3)(b). A client running three unrelated AED 200,000 workstreams doesn’t aggregate them to clear the threshold.
4. Has anyone actually thought about the free zone position? Free zone companies aren’t categorically excluded, and the analysis is more involved than a yes or no. The FAQ below has the short version, and the full free zone analysis has the long one.
We only work on R&D claims. We don’t do audit, bookkeeping, VAT or Corporate Tax compliance, which means a referral doesn’t put your core client relationship at risk. If that’s a conversation you’d rather have properly than at a stand, let’s set up a longer discussion after the event.
For finance leaders and business owners
If you’re running or financing a business that develops technology in the UAE, the most useful thing you can do before the Council’s portal opens is documentary, not procedural.
The regime asks you to demonstrate, project by project, what technological uncertainty you set out to resolve, what approach you took, and why the outcome wasn’t readily deducible by a competent professional in the field. That evidence is a lot easier to assemble while the work is happening than to reconstruct afterwards. Technical scoping, project boundary definition and contemporaneous record-keeping are all available to do right now. Our process walks through how we help teams get that in place.
Bring us a description of what your engineering or science team actually builds, and we can tell you which parts of it are likely to fall inside the regime.
Shoayb’s consideration points
These are questions I’m currently working through professionally. They aren’t settled, and they reflect where the legislation leaves genuine gaps that practitioners and clients need to think through carefully.
The treatment of in-flight R&D activity. Businesses running qualifying R&D during 2026 can’t currently apply for pre-approval, because the Council’s portal hasn’t launched. The Council holds rule-making power over the form, manner and timeline of applications under CD 215, Article 12(2), and it hasn’t published operational guidance on activity already under way. I’m not willing to state a position on how in-flight expenditure will be treated until the Council has said so. Anyone telling you confidently either way is guessing. (As at 10 September 2026.)
Parent-owned intellectual property in multinational structures. Where a UAE subsidiary performs R&D but the resulting intellectual property vests in a foreign parent, the interaction between the territorial requirement in MD 24, Article 3(3), the entity-level eligibility conditions, and transfer pricing treatment isn’t fully resolved on the face of the legislation. This affects a substantial share of the multinational R&D centres operating here. (As at 10 September 2026.)
Scenario B under CD 215, Article 3(2)(a). The narrower reading, where a Qualifying Free Zone Person retains its status while specific R&D-derived income is taxed at 9%, is available on a literal reading of the article. It isn’t confirmed by Council or FTA guidance, and I wouldn’t rely on it without written clarification. (As at 10 September 2026.)
Frequently asked questions
Can free zone companies claim?
Yes, but with conditions. Two pathways exist, and the outcome depends on where the entity sits within them. The full free zone analysis covers Pathway 1 (Scenarios A and B under CD 215), Pathway 2 (Top-up Tax under CD 215, Article 3(2)(b) and CD 142/2024), and what happens if QFZP status is lost: the entity stops being a Qualifying Free Zone Person from the start of the relevant tax period and for the four tax periods after it (MD 229/2025, Article 5(2)). The exclusion applies only to free zone companies at a pure 0% Corporate Tax position with no Top-up Tax exposure, which is a narrower group than “free zone companies” as a whole.
Is the credit paid out in cash?
No. The Phase 1 credit is non-refundable, and MD 24, Article 2(2) says so expressly. It offsets Corporate Tax and Top-up Tax liability. Any unused balance can be carried forward under CD 215, Article 6(3), subject to the restrictions in MD 24, Article 5.
Can we claim for R&D we completed in early 2026 before applying?
Pre-approval is mandatory for every R&D project under CD 215, Article 3(1)(b) and MD 24, Article 4(1), and there’s no retrospective pre-approval pathway in the legislation as drafted. How the Council will treat activity already under way when the portal opens hasn’t been addressed in published guidance. It’s one of the open questions I’ve flagged above.
Can R&D performed outside the UAE be included?
No. MD 24, Article 3(3) restricts qualifying activity to R&D conducted in the UAE.
Is there a cap on subcontracted R&D?
There’s no percentage cap on subcontracting fees in the UAE legislation. MD 24, Article 10 sets the conditions for subcontracting fees to qualify: the subcontractor has to be UAE-based, the work has to be UAE-performed, and there can be no chain subcontracting or back-to-back arrangements. Subject to those conditions, qualifying subcontracting fees can be included in full. Two other limits do apply: the amount is subject to Article 34 of the Corporate Tax Law, and subcontracting between members of the same Tax Group is excluded under MD 24, Article 10(3). The 65% cap you might be thinking of is a UK R&D claim concept and doesn’t apply here.
Next steps
- Check eligibility against the four gates
- How the claim process works
- The full MD 24 walkthrough
- What CD 215 means in practice
- Common pre-approval mistakes to avoid
- Which industries stand to benefit most
- Key considerations for advisers, published by ICAEW Middle East
- Accounting Refigured 2026, 16 September, Dubai
If you’re attending on 16 September, come and find us on the exhibition floor.